

Quick answer: IRS Currently Not Collectible (CNC) status pauses IRS collection — no levies, no garnishments, no demand for payment — when paying would prevent you from meeting basic living expenses. The IRS still records the debt and reviews your status periodically. Penalty and interest continue to accrue. CNC is right for taxpayers with no realistic ability to pay, especially fixed-income retirees.
I’m Darrin Mish. Tampa tax attorney, 32 years in, more than $100 million in IRS debt resolved. What follows isn’t theory – it’s what I’ve actually watched work.
When tax debt feels overwhelming and your finances are stretched beyond their limits, you might wonder if there's any breathing room available. The good news? The IRS recognizes that some taxpayers simply can't pay their tax debts without creating serious financial hardship. That's where IRS Currently Not Collectible status comes in. This lesser-known option can provide temporary relief from aggressive collection actions, giving you time to get back on your feet. Let's explore what this status means, how it works, and whether it might be the right solution for your situation.
What Is IRS Currently Not Collectible Status?
IRS Currently Not Collectible status is exactly what it sounds like: a determination by the IRS that your tax debt is, for now, not collectible. When you're granted this status, the IRS agrees to temporarily halt collection activities because paying your tax debt would leave you unable to meet basic living expenses.
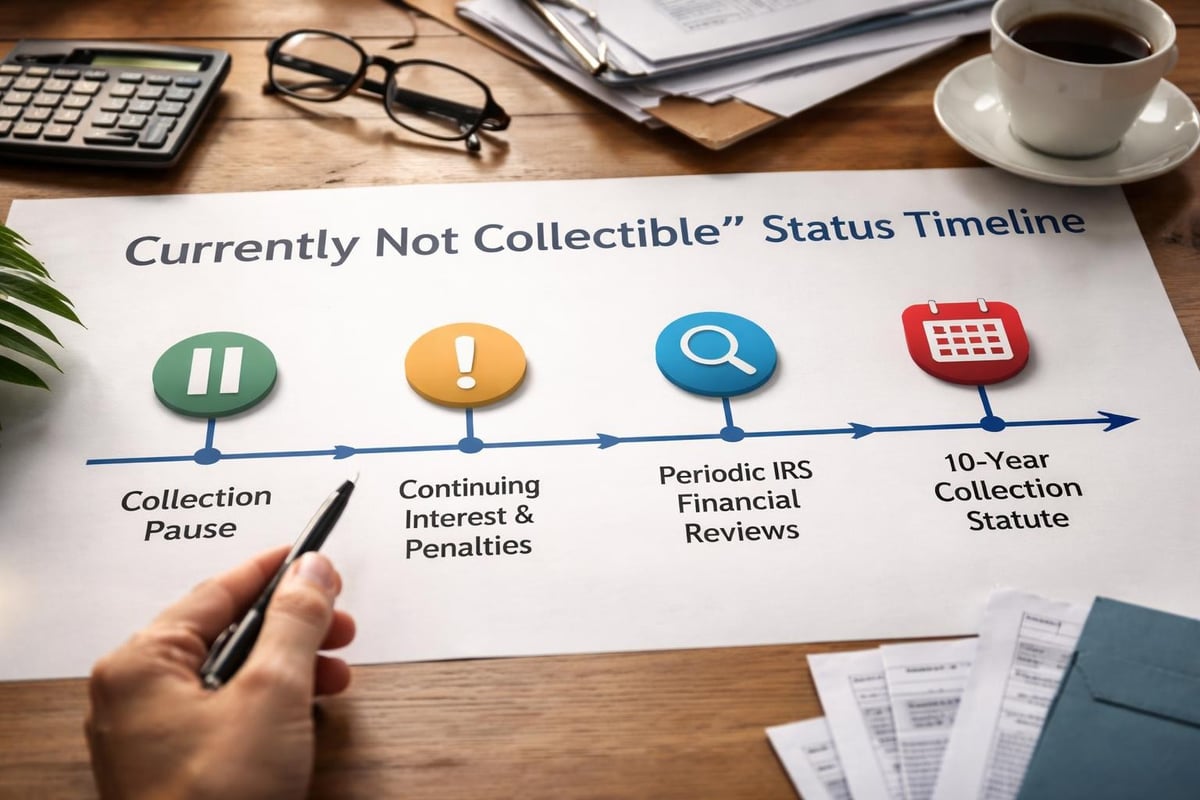
Think of it as hitting the pause button on collections. The IRS won't garnish your wages, levy your bank accounts, or seize your assets while you're in this status. However, and this is crucial, your tax debt doesn't disappear. Interest and penalties continue to accrue, and the IRS can resume collection efforts if your financial situation improves.
How It Differs From Other Tax Relief Options
You might be wondering how this compares to other solutions like installment agreements or an Offer in Compromise. Here's the distinction:
- Installment Agreement: You make monthly payments toward your debt
- Offer in Compromise: You settle your debt for less than you owe
- Currently Not Collectible: Collections are paused, but you pay nothing
The IRS's Internal Revenue Manual provides detailed guidelines on how revenue officers determine whether a taxpayer qualifies for this special status. The determination centers on one key question: Can you pay your basic living expenses and your tax debt?
Who Qualifies for Currently Not Collectible Status?
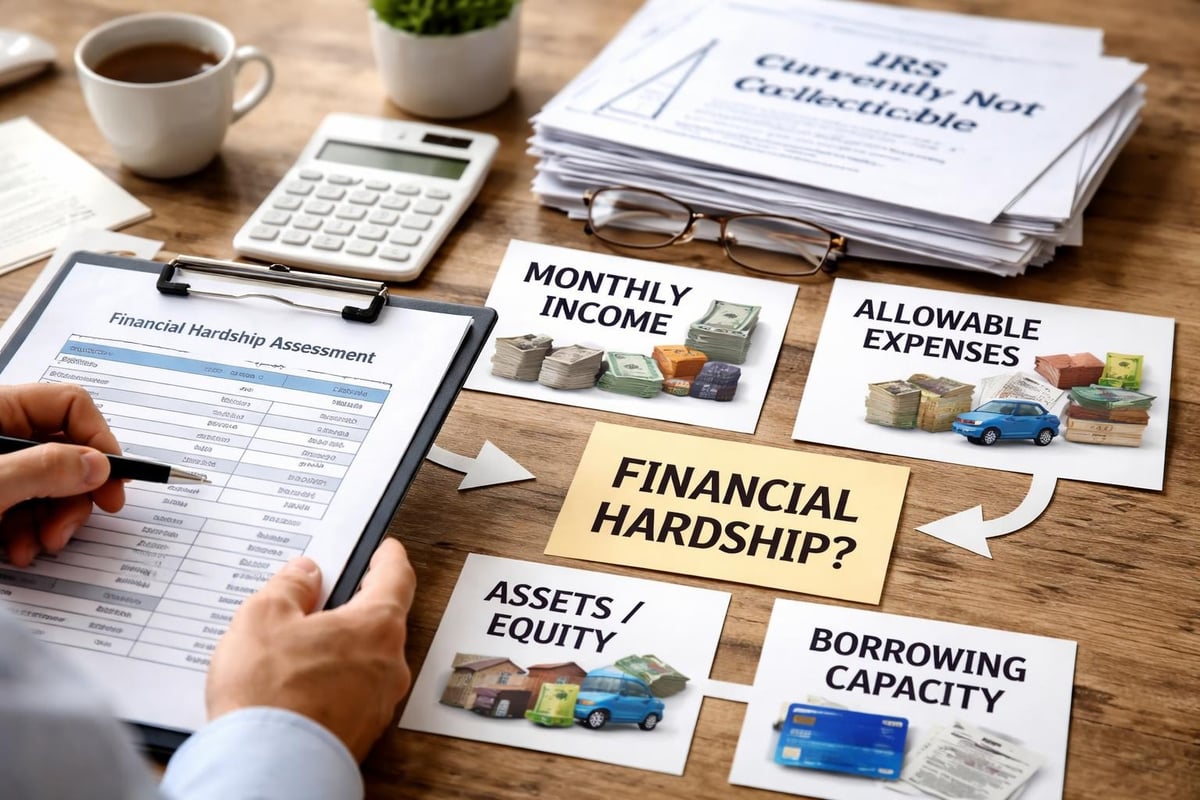
Not everyone qualifies for IRS Currently Not Collectible status. The IRS conducts a thorough financial analysis to determine eligibility. Your monthly income must be equal to or less than your allowable living expenses.
Financial Hardship Criteria
The IRS looks at several factors when evaluating your request:
- Total monthly income from all sources
- Allowable living expenses based on IRS standards
- Equity in assets like homes, vehicles, and investments
- Ability to borrow against assets or income
If paying your tax debt would prevent you from covering necessary expenses like housing, food, transportation, and medical care, you might qualify. The keyword here is "necessary." The IRS uses national and local standards to determine what counts as reasonable living expenses.
Common Situations That May Qualify
Several life circumstances often lead to approval for this status:
- Unemployment or underemployment with limited job prospects
- Serious medical conditions creating substantial expenses
- Disability preventing you from working full-time
- Fixed retirement income that barely covers essentials
- Recent bankruptcy that depleted your resources
The Taxpayer Advocate Service provides valuable information about how economic hardship factors into these determinations.
How to Request Currently Not Collectible Status
Getting an account placed in Currently Not Collectible status, what practitioners call CNC, is a documentation exercise. The IRS is not deciding whether your situation is sad. It is deciding whether the numbers on your financial statement support the conclusion that collecting right now would leave you unable to pay basic living expenses. Bring the numbers and the paperwork, and this goes smoothly. Call the IRS without them and you will spend months going in circles.
The Two Tests, Not One
Most articles on this subject describe a single test: if your allowable living expenses equal or exceed your income, you qualify. That is half of it.
The Internal Revenue Manual applies a second test to assets. Under IRM 5.16.1.2.9(1), an account should not be reported CNC if the taxpayer has income or equity in assets and enforced collection of that income or those assets would not cause hardship. So a taxpayer with no monthly surplus but real equity in a second property, a boat, or a brokerage account is not automatically in. The IRS will look at the equity first.
Both tests have to point the same direction. Thin income and thin equity gets you CNC. Thin income and fat equity usually gets you a conversation about selling something.
Step 1: Gather the Documentation Before You Call
Have all of this in hand before anyone at the IRS asks for it:
- Income. At least three months of pay stubs if you are employed. A current profit and loss statement if you are self employed. Award letters or bank statements if you receive Social Security, disability, unemployment, or pension income.
- Bank statements. Every checking, savings, and investment account, going back at least three months. The IRS is looking for liquid assets sitting idle.
- Assets. Real estate, vehicles, retirement accounts, anything with equity. Include current values and the balances owed against them.
- Monthly expenses. Rent or mortgage, utilities, insurance, transportation, out of pocket medical costs, court ordered payments. Receipts and statements, not estimates.
- Anything that explains the hardship. Medical records, a layoff notice, a disability determination. If something specific changed your ability to pay, document it.
This is where most people stumble. They reach out to the IRS first and assemble paperwork second, and the case drifts for months while the balance keeps growing.
Step 2: Pick the Right Collection Information Statement
Which form you file depends on who is handling your case, not on what you prefer.
- Form 433-F (Collection Information Statement, Rev. 7-2024) is the short form, used in the campus and Automated Collection System channels. Most wage earners dealing with ACS file this one.
- Form 433-A (Rev. 6-2026) is the long form for individuals whose case sits with a revenue officer in Field Collection.
- Form 433-B (Rev. 6-2026) is for businesses.
Fill it out completely. Blank lines get read as evasion, and an incomplete statement is the most common reason a CNC request stalls. If a number is zero, write zero rather than leaving the field empty.
Step 3: Work Out Your Allowable Living Expenses
The IRS does not accept your household budget as written. It applies the Collection Financial Standards under IRM 5.15.1, which cap certain categories at national or local figures regardless of what you actually spend.
Food, clothing, and miscellaneous expenses come from a national standard tied to household size. Housing and utilities come from a county level standard. Transportation has both an ownership cost and an operating cost component, set regionally. Out of pocket health care has a national standard per person by age.
Some expenses come in at actual cost rather than a standard, including court ordered payments, child care, and certain taxes. Some expenses the IRS will not allow at all, which is where people are most often surprised. Run your numbers against the standards before you submit, not after.
Step 4: Make the Request
Call the number on your most recent notice, or work through the revenue officer assigned to your case if you have one. Say plainly that you are requesting Currently Not Collectible status because paying would prevent you from meeting basic living expenses, and that you have a completed Collection Information Statement ready.
Keep a record of the date, the time, the name and badge number of everyone you speak with, and what was said. If you later have to escalate, that log is the difference between a fact and your recollection.
Step 5: Respond Immediately to Follow Up Requests
The IRS will usually come back asking for something: a missing bank statement, verification of an expense, a more recent pay stub. Those requests carry deadlines, and missing one can close the case and restart collection. Answer within days, not weeks.
What Unfiled Returns Actually Do to a CNC Request
Here is where a lot of websites get it wrong, including plenty that should know better.
The common claim is that every relief program requires every return to be filed first, no exceptions. For most programs that is accurate. For hardship CNC it is not.
IRM 5.16.1.2.9(12) is explicit: accounts may be reported CNC hardship if a Collection Information Statement can be verified, even where returns are unfiled. The Caution immediately above it goes further, and says a levy cannot be issued or left in place to pressure a taxpayer into filing once hardship has been verified. The campus manual says the same thing at IRM 5.19.17.2.4.1 and grounds it in Vinatieri v. Commissioner, 133 T.C. 392 (2009).
Filing compliance is still the general rule under IRM 5.16.1.2(5), and you should file. Unfiled returns will block an Offer in Compromise or an installment agreement outright, and the failure to file penalty runs at ten times the failure to pay penalty. But if you are being levied right now and you have years of unfiled returns, verified hardship can get that levy released before the returns are done. Anyone who tells you to just accept the levy until you have filed everything is costing you money.
What Status 53 Means on Your Transcript
When the IRS grants CNC, it closes the module with transaction code 530 and the account moves to status 53. That is what you will see on a transcript, and it is why people search for “IRS uncollectible status 53.”
Two things worth knowing about that number. First, every TC 530 carries a closing code that explains why the account was closed, and the hardship codes run from 24 through 32. There is no closing code 53. The 53 is the account status, not the reason. Second, status 53 does not always mean CNC. A module can sit in status 53 for unrelated reasons, including certain adjustment conditions.
There is also an internal Form 53, Report of Currently Not Collectible Taxes, referenced at IRM 5.16.1.1.7. A revenue officer prepares it. It is not something you file, so treat any service that offers to “file your Form 53” with suspicion.
Which Manual Governs Your Case
CNC is run out of two different parts of the Internal Revenue Manual depending on where your case lives. Field Collection cases, the ones assigned to a revenue officer, follow IRM 5.16.1. Campus and ACS cases follow IRM 5.19.17, with the financial workup rules in IRM 5.19.13. Both channels run the underlying financial analysis under IRM 5.15.1.
This matters more than it sounds. The same facts can get a different answer depending on which channel is holding the case, and knowing which manual applies is the difference between citing the rule that governs and citing one that does not.
What Happens While You're in CNC Status?
Once the IRS grants you Currently Not Collectible status, several things occur simultaneously. Understanding both the benefits and the limitations helps you plan accordingly.
The Good News
| Benefit | What It Means |
|---|---|
| No wage garnishments | Your paycheck remains intact |
| No bank levies | Your accounts are protected |
| No asset seizures | The IRS won't take your property |
| Relief from pressure | Collection notices stop |
| Time to recover | You can focus on improving your finances |
The immediate relief can feel life-changing. When you're struggling to pay rent and buy groceries, not having the IRS garnishing your wages makes a real difference.
The Reality Check
However, Currently Not Collectible status isn't a permanent solution:
- Interest continues accruing on your tax debt at the federal rate
- Penalties keep adding up unless you've qualified for penalty abatement
- Your debt grows larger each month you're in this status
- The statute of limitations keeps running (usually 10 years from assessment)
- Tax refunds will be seized and applied to your balance
The IRS also periodically reviews your financial situation. If your income increases or your expenses decrease, they may remove you from CNC status and resume collection activities.
How Long Does CNC Status Last?
There's no fixed duration for IRS Currently Not Collectible status. It lasts as long as your financial hardship continues and the collection statute hasn't expired.
IRS Review Process
The IRS conducts periodic reviews to reassess your financial situation:
- Reviews typically occur every 1-2 years
- You may need to submit updated financial information
- The IRS can also review if they receive information suggesting your finances improved
- You must respond promptly to review requests to maintain your status
Some taxpayers remain in this status for years, while others see their situations improve more quickly. The key is understanding that it's a temporary measure, not a permanent fix.
When CNC Status Ends
Your Currently Not Collectible status terminates when:
- Your financial situation improves sufficiently
- The 10-year collection statute expires
- You fail to respond to IRS review requests
- You receive a large tax refund (indicating underwithheld taxes)
- You acquire significant assets or income
If your status ends due to improved finances, the IRS will resume collection efforts. This might mean setting up a payment plan or exploring other relief options.
Strategic Considerations and Alternatives
While IRS Currently Not Collectible status provides immediate relief, it's worth considering whether it's your best long-term option. Sometimes, other solutions make more sense financially.
Comparing Your Options
| Solution | Stops Collections | Reduces Debt | Monthly Payment | Best For |
|---|---|---|---|---|
| CNC Status | Yes | No | $0 | Severe hardship |
| Installment Agreement | Yes | No | Varies | Stable income |
| Offer in Compromise | Yes | Yes | Varies | Inability to pay full amount |
| Penalty Abatement | No | Partially | N/A | First-time penalty situations |
If you're considering settling with the IRS, an Offer in Compromise might resolve your debt permanently for less than you owe. However, qualifying is more difficult than getting CNC status.
The Growing Debt Problem
Here's something many people don't consider initially: while you're in Currently Not Collectible status, your debt continues growing. A $25,000 tax debt at 6% interest adds $1,500 annually. Over three years in CNC status, you'd owe over $4,500 more just in interest.
This reality makes the 10-year collection statute important. If you can remain in CNC status until the statute expires, the IRS can no longer collect the debt. However, this strategy requires careful monitoring and professional guidance.
Common Mistakes to Avoid
When dealing with IRS Currently Not Collectible status, taxpayers often make errors that complicate their situations. Avoiding these pitfalls protects your status and your future options.
Documentation Errors
The most frequent mistakes include:
- Underreporting income or failing to disclose all sources
- Omitting assets like second vehicles or investment accounts
- Inflating expenses beyond IRS allowable standards
- Missing deadlines for providing requested information
- Ignoring IRS correspondence during review periods
The IRS has access to extensive financial data through third-party reporting. Attempting to hide income or assets can result in denial of your request and potentially fraud charges.
Ongoing Compliance Requirements
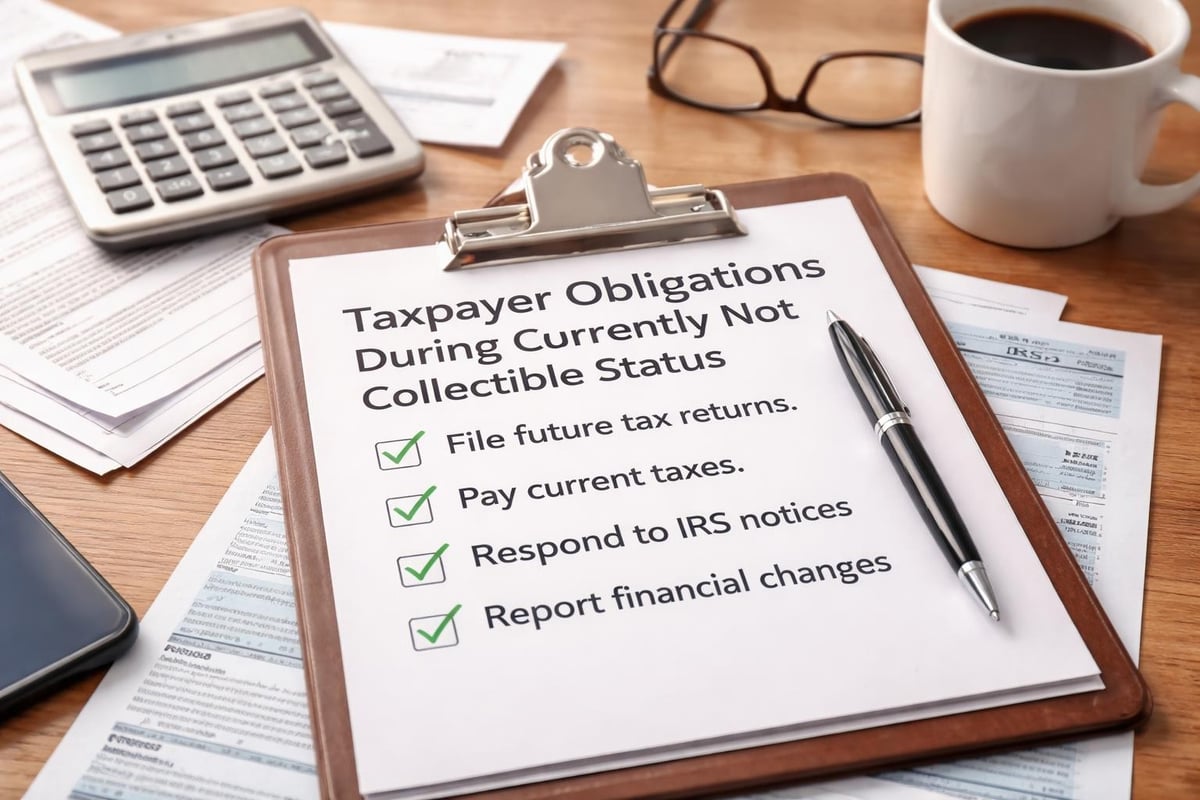
Even while in CNC status, you must:
- File all future tax returns on time
- Pay all current tax obligations as they come due
- Respond to IRS notices promptly
- Report significant financial changes to the IRS
- Maintain accurate records of your financial situation
Failing to file returns or pay current taxes can immediately terminate your Currently Not Collectible status. The IRS views these as signs you're not acting in good faith to resolve your tax problems.
Working With Tax Professionals
Navigating IRS Currently Not Collectible status can feel overwhelming, especially when you're already dealing with financial stress. Professional guidance often makes the difference between approval and denial.
What Tax Attorneys Bring to the Table
Experienced tax professionals understand:
- Which expenses the IRS considers allowable
- How to present financial information persuasively
- What documentation strengthens your case
- How to negotiate with revenue officers effectively
- When CNC status is the best option versus alternatives
A tax attorney can also help you understand how tax debt relates to other financial challenges you might be facing, like bankruptcy or debt settlement.
The Value of Experience
According to Debt.org, taxpayers who work with tax professionals often achieve better outcomes in their dealings with the IRS. Professionals know how to avoid common pitfalls and can advocate on your behalf throughout the process.
This is particularly important if you're also dealing with unfiled tax returns or wage garnishment situations that need immediate attention.
Life After Currently Not Collectible Status
Eventually, your financial situation will likely improve, or the collection statute will expire. Planning for what comes next ensures you're prepared when CNC status ends.
Building Toward Resolution
While in Currently Not Collectible status, consider:
- Improving your financial literacy to prevent future tax problems
- Building emergency savings when possible
- Increasing your income through education or skill development
- Monitoring the statute of limitations on your tax debt
- Exploring long-term solutions like an Offer in Compromise
Some taxpayers use the breathing room CNC status provides to prepare for a more permanent solution. You might save up a lump sum to propose an Offer in Compromise or improve your income enough to afford a reasonable installment agreement.
Preventing Future Tax Debt
Learning from this experience helps you avoid repeating it:
- Adjust your withholding to match your actual tax liability
- Make estimated tax payments if you're self-employed
- Set aside money regularly for tax obligations
- Consider working with a tax professional for tax planning
- Stay current with all filing and payment requirements
The goal isn't just to survive this tax debt, but to build habits that prevent creating new debt.
Understanding Your Rights and Protections
As a taxpayer dealing with the IRS, you have specific rights protected by law. Understanding these rights empowers you throughout the Currently Not Collectible process.
Taxpayer Bill of Rights
You have the right to:
- Be informed about your tax obligations
- Quality service from IRS employees
- Pay only the correct amount of tax
- Challenge the IRS's position and be heard
- Appeal IRS decisions in an independent forum
- Finality in knowing the maximum time the IRS has to collect
- Privacy and confidentiality
- Professional and courteous treatment
- Representation before the IRS
The Taxpayer Advocate Service serves as an independent organization within the IRS that helps taxpayers resolve problems and ensures these rights are protected.
When to Seek Additional Help
Consider escalating your case if:
- The IRS denies your CNC request despite clear hardship
- Revenue officers treat you unprofessionally
- You face immediate enforcement action despite pending review
- Your financial information is handled improperly
- Standard procedures aren't resolving your situation
Tax attorneys can help you navigate appeals processes and ensure the IRS follows proper procedures in your case.
IRS Currently Not Collectible status offers essential relief when financial hardship makes tax debt impossible to pay, but it requires careful documentation and ongoing compliance. While this status pauses collection activities, your debt continues growing, making professional guidance valuable for long-term planning. If you're struggling with overwhelming tax debt and need expert help navigating your options, the Law Offices of Darrin T. Mish, P.A. offers free consultations to help you understand your best path forward, whether that's CNC status or another solution tailored to your unique situation.
How to Apply for IRS Currently Not Collectible Status
- Step 1: Confirm CNC is the right move CNC pauses collection but doesn’t eliminate debt. Penalties and interest keep accruing. CNC is right when no realistic ability to pay exists for the foreseeable future.
- Step 2: File any missing tax returns The IRS requires compliance before granting CNC. Pull your account transcripts and file every missing return — even if you can’t pay.
- Step 3: Build your Form 433-F or 433-A Document monthly income and allowable expenses (housing, transportation, food, healthcare). Show that monthly disposable income is at or near zero. Use national/local IRS standards plus actual receipts.
- Step 4: Call the IRS to request CNC verbally Often fastest. Call the number on your most recent notice or the Practitioner Priority Service. Have your 433-F ready and request ‘currently not collectible’ status.
- Step 5: Respond to follow-up document requests The IRS may ask for bank statements, paystubs, or expense receipts. Respond promptly with what they ask for. Delays often kill CNC applications.
- Step 6: Watch for periodic review notices The IRS reviews CNC status annually based on your tax return income. If income rises, the IRS may revoke CNC and demand a new financial. Stay on top of this.