

Most of what you've read online about IRS problems is wrong, or at least misleading. I'm Darrin Mish. I practice tax law in Tampa and I've been doing this for 32 years. Here's what's actually true.
I'm Darrin Mish. Tampa tax attorney, 32 years in, more than $100 million in IRS debt resolved. What follows isn't theory. It's what I've actually watched work.
Living in Wesley Chapel means you've seen this community transform from rural Pasco County backroads into a thriving suburb with new construction, growing businesses, and residents who commute into Tampa or run their own shops. That growth brings opportunity. It also brings IRS problems when income jumps, quarterly estimates fall behind, or a failed business leaves payroll tax debt. Working with a wesley chapel fl tax attorney irs debt specialist isn't about finding loopholes. It's about knowing which relief programs you actually qualify for and how to structure them so the IRS says yes.
The IRS doesn't care that your contractor business boomed in 2024 and crashed in 2025. They don't factor in your mortgage, your kids' tuition, or the fact that you drained savings keeping employees paid. They care about their formula, their timelines, and their collection statistics. That's where representation changes outcomes.
Why IRS Debt Hits Wesley Chapel Residents Hard
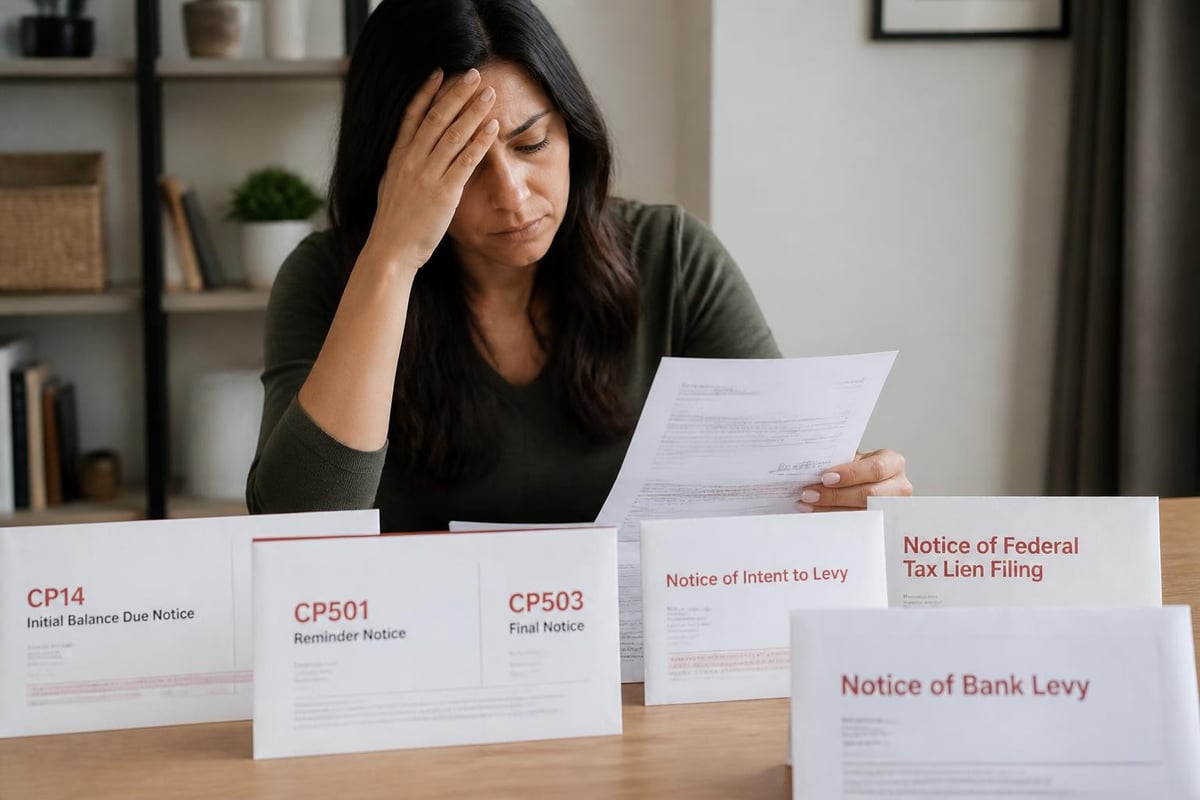
You bought into a master-planned community expecting stability. Then the IRS sends Notice CP14, then CP501, then CP503. Maybe you ignored them because the numbers felt impossible. Maybe you tried calling the IRS and waited on hold for three hours before the line dropped.
Self-employed tradespeople, real estate agents, and small business owners make up a large chunk of Wesley Chapel's workforce. That means irregular income, estimated tax payments you hope to catch up on later, and 1099 forms that pile up faster than W-2 wage earners ever see. The IRS flags self-employment income aggressively. One missed quarterly payment becomes a rolling balance with penalties and interest compounding daily.
Here's what typically happens:
- You owe $18,000 from 2023 and 2024 combined.
- Penalties add 25% for failure to pay.
- Interest compounds daily at the federal short-term rate plus 3%.
- By the time you open the notice, the balance is $24,000.
The IRS sent you letters. You didn't respond. Now they're moving to enforce collection, and that means tax liens on your property or levies against your bank account.
What the IRS Can Actually Do to Collect
The IRS has tools most creditors don't. They don't need to sue you to freeze your bank account. They don't need a court order to garnish your wages. They file a Notice of Federal Tax Lien with Pasco County’s property records, and suddenly refinancing your house becomes impossible.
Liens vs. Levies
A lien is a public claim against your property. It attaches to your house, your car, your business assets. It doesn't take anything from you immediately, but it wrecks your credit and blocks sales or refinances. The IRS files liens once your balance crosses roughly $10,000 and you've ignored their notices for months.
A levy is direct seizure. The IRS can take funds from your bank account, garnish up to 25% of your paycheck, or intercept your federal and state tax refunds. Levies happen after the lien, after more notices, after you've had multiple chances to respond. They're not the IRS's first move, but once they start, stopping them requires immediate action.
The IRS guidance on resolving tax debt lists your options in bureaucratic language. What it doesn't tell you is which option the IRS will actually approve for someone in your financial situation.
Wesley Chapel FL Tax Attorney IRS Debt Relief Programs That Work
You've got four realistic paths if you owe the IRS and can't pay in full today. Each has specific qualifications, and the IRS rejects most applications from taxpayers who file without representation. Not because the taxpayer lied. Because they didn't structure the request to match IRS formulas.
Offer in Compromise
An Offer in Compromise (OIC) lets you settle your debt for less than you owe. The IRS accepts roughly 40% of offers submitted. That number drops below 20% for taxpayers who file without an attorney.
Here's the IRS formula: they calculate your reasonable collection potential (RCP) by adding your net equity in assets to your future income over 12 or 24 months. If you offer an amount equal to or greater than your RCP, they'll consider it. If your offer is $15,000 and your RCP is $22,000, the IRS rejects it automatically.
You might qualify if:
- Your income recently dropped (retirement, disability, business failure).
- Your expenses exceed IRS allowable standards (medical bills, elder care).
- Your assets carry little equity after mortgages and secured debts.
I've negotiated offers as low as $3,000 to settle $80,000 in debt. I've also seen the IRS reject offers from people who legitimately couldn't pay because the application didn't document their hardship correctly. The IRS’s official Offer in Compromise guidance walks through the process, but it doesn't explain how to package your financials so a revenue officer believes you.
Installment Agreements
An installment agreement is a payment plan. You owe $30,000, you pay $450 a month for 72 months. Simple. Except the IRS charges setup fees, continues adding interest, and demands full financial disclosure for balances over $50,000.
| Agreement Type | Balance Limit | Financial Disclosure Required | Setup Fee |
|---|---|---|---|
| Guaranteed | Under $10,000 | No | $31–$225 |
| Streamlined | $50,000 or less | No | $31–$225 |
| Partial Payment | Over $50,000 | Yes (Form 433-A or 433-F) | $31–$225 |
You can request an installment agreement online if your balance is under $50,000 and you've filed all required returns. The IRS usually approves these within a week. If you owe more, or if you want a partial-payment plan (monthly payments that don't fully pay off the debt within the collection statute), you'll need to submit detailed financials and probably deal with a revenue officer. That's where a wesley chapel fl tax attorney irs debt specialist earns the fee.
Currently Not Collectible Status
Currently Not Collectible (CNC) status tells the IRS, "I can't pay anything right now, and forcing collection would create a hardship." The IRS suspends collection activity. They don't forgive the debt. They stop levies and liens while you're in CNC, but interest and penalties keep accruing.
You qualify if your income barely covers your allowable living expenses. The IRS uses national and local standards: housing, transportation, food, medical. If you're retired on Social Security, unemployed, or dealing with serious illness, CNC might be your best short-term move. The IRS will review your status periodically, and if your income improves, they'll restart collection.
This isn't a permanent solution. It's a pause. But it's a legitimate pause, and it stops aggressive collection while you rebuild.
Penalty Abatement
The IRS tacks on penalties for failure to file (5% per month, up to 25%) and failure to pay (0.5% per month, up to 25%). On a $40,000 balance, penalties can add $20,000. Interest is required by law. Penalties aren't.
You can request first-time penalty abatement if you've filed and paid on time for the prior three years and you don't have other penalties. The IRS grants this almost automatically if you meet the criteria. You call, you ask, they remove the penalties. That's thousands of dollars.
Reasonable cause abatement requires proof that you couldn't file or pay due to circumstances beyond your control: death in the family, fire, serious illness, natural disaster. The IRS reads "reasonable cause" narrowly. "I forgot" doesn't work. "I was hospitalized for six weeks and couldn't access my records" might.
When You Actually Need a Tax Attorney
The IRS gives you tools to resolve debt on your own. The IRS landing page on tax debt help links to forms, payment calculators, and instructions. So when does paying an attorney make sense?
You need representation if:
-
Your balance exceeds $50,000. The IRS assigns a revenue officer, and you're negotiating directly with someone who has authority to levy and seize. Revenue officers are polite, professional, and relentless. They will ask for financials you don't want to hand over without review.
-
You own a business with payroll tax debt. The IRS treats payroll taxes (trust fund taxes) differently. They can assess the Trust Fund Recovery Penalty against you personally, even if your business is an LLC or corporation. Payroll tax problems spiral fast, and the IRS moves aggressively because it's "their money" withheld from employees.
-
The IRS has already filed a lien or issued a levy. Once enforcement starts, reversing it requires immediate financial disclosure and negotiation. You've got 30 days to request a Collection Due Process hearing after a levy notice. Miss that window and your options narrow.
-
You're facing an audit. IRS audits start as letters asking for documentation. They escalate into office interviews or field audits where an agent visits your business. Anything you say can increase your liability. Tax attorneys operate under attorney-client privilege. CPAs and enrolled agents don't.
-
You've got unfiled returns going back years. The IRS won't negotiate payment until you file everything. If you're missing returns from 2019, 2020, 2021, and 2022, the IRS will file Substitutes for Return (SFRs) using third-party data. SFRs always maximize your liability because they don't include deductions or credits you're entitled to. Filing corrected returns after an SFR requires navigating the IRS's account adjustment process.
The National Taxpayer Advocate’s annual report documents how often taxpayers lose appeals, installment plans, and offers because they didn't understand the IRS's process. The system isn't designed to be intuitive.
How Wesley Chapel FL Tax Attorney IRS Debt Representation Works
You call, we talk, I ask about your situation. What do you owe? What years? Have you filed everything? Are you getting notices? That first conversation is free, and it tells me whether I can help you and what the likely outcome looks like.
If we move forward, you sign a Power of Attorney (Form 2848). That form gives me authority to speak with the IRS on your behalf. Once it's filed, IRS calls and letters come to me, not you. That alone drops your stress level by half.
Here's the typical process:
-
Pull your IRS transcripts. I order Account Transcripts and Wage & Income Transcripts for every year in question. These show exactly what the IRS has on file, what you've paid, what penalties they've assessed, and whether you have unfiled returns.
-
File missing returns. If you're missing years, we prepare and file them. The IRS won't negotiate until your filing compliance is current.
-
Analyze your financials. I collect your income, expenses, assets, and liabilities. Then I compare them to IRS allowable standards to see what you actually qualify for.
-
Choose the right relief program. If your RCP is low, we file an Offer in Compromise. If you've got steady income but can't pay in full, we request an installment agreement. If you're broke, we apply for Currently Not Collectible status.
-
Negotiate with the IRS. Most cases settle without ever speaking to a revenue officer. Some require phone calls, written explanations, and Appeals hearings. I handle all of it.
You'll know what's happening at each step. I don't ghost clients, and I don't hand your case to a paralegal after the first meeting. You hired an attorney. You get an attorney.
What It Costs and What You're Paying For
Fees vary based on complexity. A simple installment agreement might run $1,500 to $2,500. An Offer in Compromise typically costs $3,500 to $7,500. A business with payroll tax issues and multiple years of unfiled returns can run $10,000 or more.
You're not paying for forms. You're paying for judgment. The IRS offers installment agreements to almost anyone who asks. But should you take a 72-month payment plan if you'd qualify for Currently Not Collectible? Should you offer $8,000 to settle when your RCP is only $5,000? Should you fight a Trust Fund Recovery Penalty or accept it and move on?
Tax attorney fees buy you:
-
Correct strategy. I've resolved over $100 million in IRS debt. I know which revenue officers accept reasonable cause abatement and which demand documentation for every claimed expense. I know which Appeals officers settle and which fight.
-
Attorney-client privilege. Anything you tell me is protected. The IRS can't subpoena our conversations. CPAs and enrolled agents don't have that protection.
-
Access. When the IRS assigns a revenue officer, I call them directly. When your case goes to Appeals, I file briefs and attend hearings. You don't sit on hold.
I explain tax resolution attorney fees in detail on the site. No surprises, no hidden costs.
Avoiding IRS Scams and Tax Relief Mills
You've seen the TV ads. "Settle your IRS debt for pennies on the dollar!" "We settled $400,000 for only $12,000!" Most of those companies are lead generators. They charge you $5,000 upfront, assign your case to an unlicensed "case manager," file cookie-cutter forms, and disappear when the IRS rejects your offer.
The FTC warns about IRS impersonation scams and tax relief fraud. If someone cold-calls you claiming they can stop IRS collection immediately, hang up. The IRS doesn't work that way, and neither do legitimate attorneys.
Red flags:
- Guaranteed outcomes. No attorney can guarantee the IRS will accept an offer or approve a payment plan.
- Pressure to pay upfront before reviewing your financials. Ethical attorneys assess your case before quoting fees.
- Claims that they have "inside contacts" at the IRS. The IRS doesn't play favorites.
- Unlicensed staff handling substantive work. Your case should be managed by an attorney, CPA, or enrolled agent, not a salesperson.
You can verify an attorney's credentials through The Florida Bar’s board certification page. Tax law is a recognized specialty. Not every tax attorney is board certified, but if someone claims certification, you can check.
What Happens If You Do Nothing
Ignoring IRS debt doesn't make it disappear. The IRS has a 10-year collection statute (the Collection Statute Expiration Date, or CSED). After 10 years from the date they assessed the tax, they generally can't collect. But they can extend that statute by filing liens, submitting Offers in Compromise, or obtaining court judgments.
The Justice Department’s guidance on federal tax collection explains post-assessment enforcement. Once your CSED runs out, the debt legally expires. But waiting 10 years while the IRS garnishes your wages, seizes refunds, and files liens isn't a strategy.
Here's what actually happens:
- The IRS files a Notice of Federal Tax Lien, tanking your credit.
- They levy your bank account, wiping out your checking balance.
- They garnish your paycheck, leaving you with barely enough to cover rent.
- They seize your tax refunds every year until the balance is paid.
You can't discharge IRS debt in bankruptcy unless it's at least three years old, you filed returns on time, and the IRS assessed the tax at least 240 days before you filed bankruptcy. Even then, liens survive bankruptcy. The debt might be gone, but the lien stays attached to your property.
Working with the Law Offices of Darrin T. Mish
Wesley Chapel sits 25 minutes north of my Tampa office. I've worked with clients from Pasco County for decades, handling everything from small balance due notices to multi-year payroll tax disasters. Most cases settle without you ever stepping into a courtroom. Some require Appeals hearings or Collection Due Process litigation. I handle both.
You're hiring an attorney with 32 years of IRS representation, not a tax mill that farms cases to contract CPAs. I review your financials personally. I make the strategy calls. I negotiate with the revenue officer or Appeals officer assigned to your case. You'll get my cell number, and when you call, I'll answer.
The process starts with a free consultation. We'll talk about what you owe, what the IRS has done so far, and what your realistic options look like. No sales pitch. No pressure. Just a clear explanation of where you stand and what happens next.
IRS debt doesn't resolve itself, and waiting only raises the stakes. The IRS has more tools, more time, and more patience than you do. If you're facing collection in Wesley Chapel, the right attorney makes the difference between a workable payment plan and a levy that drains your account. For 32 years, I've been the attorney taxpayers call when the notices stop feeling like paperwork and start feeling like a crisis. Let's talk about your case and figure out the right move. Law Offices of Darrin T. Mish, P.A.