

There's the version of tax resolution the late-night commercials sell you. Then there's how it actually works. I'm Darrin Mish, a Tampa tax attorney. I've spent 32 years on the inside of these cases. Here's the real version.
I'm Darrin Mish. Tampa tax attorney, 32 years in, more than $100 million in IRS debt resolved. What follows isn't theory. It's what I've actually watched work.
You're carrying $40,000 in back taxes and wondering if bankruptcy will make it disappear. The short answer: maybe a piece of it, probably not all of it, and definitely not without clearing some strict hurdles. The idea that you can discharge IRS tax debt bankruptcy Chapter 7 and walk away clean is optimistic. Most federal tax debt survives bankruptcy. But some of it doesn't.
The Rules That Decide Which Tax Debt Actually Goes Away
Chapter 7 bankruptcy wipes out qualifying debts. Tax debt can qualify, but only if it meets every element of a three-part test plus two bonus conditions. Miss one, the debt stays. The IRS doesn't make this easy.
The Three-Year Rule
The tax return triggering the debt must have been due at least three years before you filed bankruptcy. For a 2020 return normally due April 15, 2021, you'd need to wait until April 15, 2024 to file Chapter 7 if you want a shot at discharge. Extensions shift the deadline. If you filed an October 2021 extension for your 2020 return, the clock doesn't start until October 15, 2021.
The IRS counts calendar days, not good intentions. Filing your bankruptcy petition even one day early restarts the analysis and disqualifies that year's debt entirely.
The Two-Year Rule
You must have actually filed the return at least two years before your bankruptcy filing. This trips up people who relied on IRS-prepared substitute returns. If the IRS filed a Substitute for Return (SFR) on your behalf because you never filed, that debt is never dischargeable. The IRS doesn't consider an SFR a "return" under 11 U.S.C. § 523. You have to file it yourself.
Late filers sometimes think they're clever: file now, wait two years, discharge the debt. That works only if you also satisfy the three-year rule. Both clocks run independently.
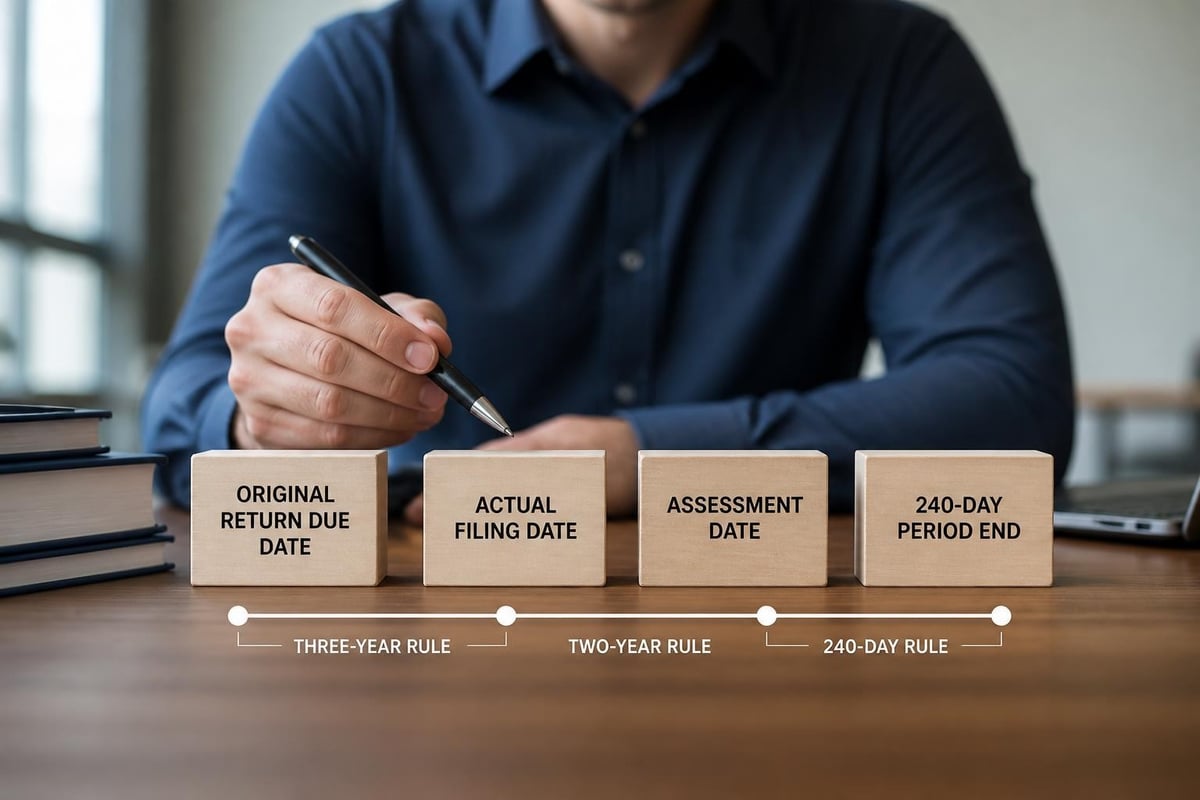
The 240-Day Rule
The IRS must have assessed the tax at least 240 days before you filed bankruptcy. Assessment happens when the IRS posts the liability to your account, usually shortly after you file or after they complete an audit. If you challenged the assessment through an Offer in Compromise or an audit appeal, the 240-day clock pauses while the IRS considers your case, then restarts when they issue a final decision.
Some taxpayers try to game the clock by filing an Offer just to delay collection. The IRS knows this. When they reject your Offer and the 240 days resume, you may find yourself further from discharge, not closer.
Income Tax Versus Payroll Tax: The Line That Doesn't Move
Only income tax can be discharged. Payroll taxes are trust fund taxes, money you withheld from employees' paychecks but never sent to the IRS. Congress decided those funds never belonged to you in the first place, so bankruptcy can't erase them. Same rule for the employer's matching portion. If you're a small business owner who stopped paying payroll tax during a cash crunch, Chapter 7 will not help.
The IRS breaks payroll tax assessments into two pieces: the trust fund portion (employee withholdings) and the employer match. Both survive bankruptcy. Personal income tax follows different rules and might qualify if it meets the timing tests.
What Happens When You Committed Fraud or Never Filed
Fraudulent returns disqualify the debt forever. If you claimed fake deductions, hid income offshore, or filed a return the IRS can prove was designed to deceive, that debt will outlive you. Same rule applies to willful evasion. The IRS doesn't need a criminal conviction. They just need to show you acted intentionally to dodge the tax.
Unfiled returns create non-dischargeable debt, period. The IRS calls them SFRs when they file on your behalf, and courts universally hold that an SFR is not a return for bankruptcy purposes. You need to file every missing return yourself, wait two years, and then assess whether discharge is possible. Skipping this step is the single biggest mistake I see from taxpayers trying to use Chapter 7 for tax relief.
| Debt Type | Dischargeable in Chapter 7? | Key Condition |
|---|---|---|
| Income tax (timely filed, 3+ years old) | Yes | Must meet all five tests |
| Income tax (SFR or unfiled) | No | Never dischargeable |
| Payroll tax (trust fund) | No | Trust funds are non-dischargeable |
| Payroll tax (employer match) | No | Non-dischargeable by statute |
| Fraudulent or willfully evaded tax | No | Fraud disqualifies permanently |
| Penalties on dischargeable tax | Yes | Penalty follows the underlying tax |
| Penalties on non-dischargeable tax | No | Penalty follows the underlying tax |
Tax Liens Survive Even When the Debt Is Discharged
Here's where people get burned. Even if you successfully discharge IRS tax debt bankruptcy Chapter 7, any tax lien filed before your bankruptcy survives. The lien attaches to property you owned on the filing date, and it doesn't release until the IRS gets paid or the collection statute expires.
Discharge eliminates your personal liability. You don't owe the money anymore. But the lien remains on your house, your car, any real property titled in your name. If you sell that house five years later, the IRS gets paid from the proceeds before you see a dime. This is the gap between discharge and release, and most taxpayers don't see it coming until closing day.
The IRS files a Notice of Federal Tax Lien when your balance exceeds a threshold, currently around $10,000 for most cases. Once filed, the lien is public record. Bankruptcy discharges your obligation to pay but doesn't remove the lien from your property. You'd need to pay the debt in full or negotiate a lien withdrawal separately.
Penalties and Interest: What Gets Wiped and What Sticks
Penalties follow the underlying tax. If the income tax is dischargeable, so are the penalties assessed on that tax. If the tax survives bankruptcy, the penalties stay too. Interest works the same way, but with a timing wrinkle: only interest that accrued before the bankruptcy petition gets discharged. Post-petition interest on non-dischargeable tax keeps running, and the IRS will bill you for it.
Penalty abatement is often a better strategy than bankruptcy for old tax debt with heavy penalties. If you have reasonable cause for late filing or late payment, the IRS might remove penalties entirely without the cost and credit damage of Chapter 7. I've resolved penalties that doubled a client's balance, turning a $50,000 debt into $28,000 overnight. That beats discharge because there's no lien, no bankruptcy on your record, and no trustee asking about your assets.
How Chapter 7 Trustees Treat Tax Refunds and Non-Exempt Property
When you file Chapter 7, a trustee is appointed to liquidate your non-exempt assets and distribute the proceeds to creditors. Your tax refund for the year you filed bankruptcy is considered part of the bankruptcy estate. If you're owed a $6,000 refund and you file in March before it arrives, the trustee can take it.
Florida exemptions are relatively generous for homestead and some personal property, but they don't protect cash or tax refunds. If you're planning to discharge IRS tax debt bankruptcy Chapter 7, file after you've received and spent (on necessities) any expected refund. Timing matters.
The trustee will also review prior tax returns to confirm your income and look for hidden assets. Lying on your bankruptcy schedules is perjury. I've seen cases dismissed and taxpayers prosecuted for hiding bank accounts or understating income. The IRS already has your transcripts. The trustee will get them too.
The Bankruptcy Means Test and Tax Debt
Chapter 7 has an income threshold. If your household income for the six months before filing exceeds the median for your state and household size, you must pass a means test showing you can't afford a Chapter 13 repayment plan. Tax debt doesn't create an automatic exemption from the means test.
High earners who owe old tax debt sometimes fail the means test and get pushed into Chapter 13, which requires a three-to-five-year repayment plan. Chapter 13 doesn't discharge tax debt the same way. Instead, it consolidates the debt into the plan and may reduce or eliminate penalties, but you're still paying a chunk of the principal. For some clients, this is better than Chapter 7. For others, it's a waste of time compared to negotiating an Offer in Compromise directly with the IRS.
Timing the Petition: When to File and When to Wait
Filing too early disqualifies debt that might have cleared if you'd waited six more months. I had a client with $22,000 in 2020 tax debt who filed Chapter 7 in January 2024. His return was due April 15, 2021. He missed discharge by three months. Had he waited until mid-April, the debt would have cleared. Instead, it survived, the lien stayed, and he spent another two years negotiating a payment plan.
Before filing, map every year of debt against the three-year, two-year, and 240-day rules. If even one year of significant debt doesn't meet all five tests, ask whether waiting will improve the outcome. If your largest debt is from 2022 and it's only October 2025, filing now saves none of it. Wait until April 2026.
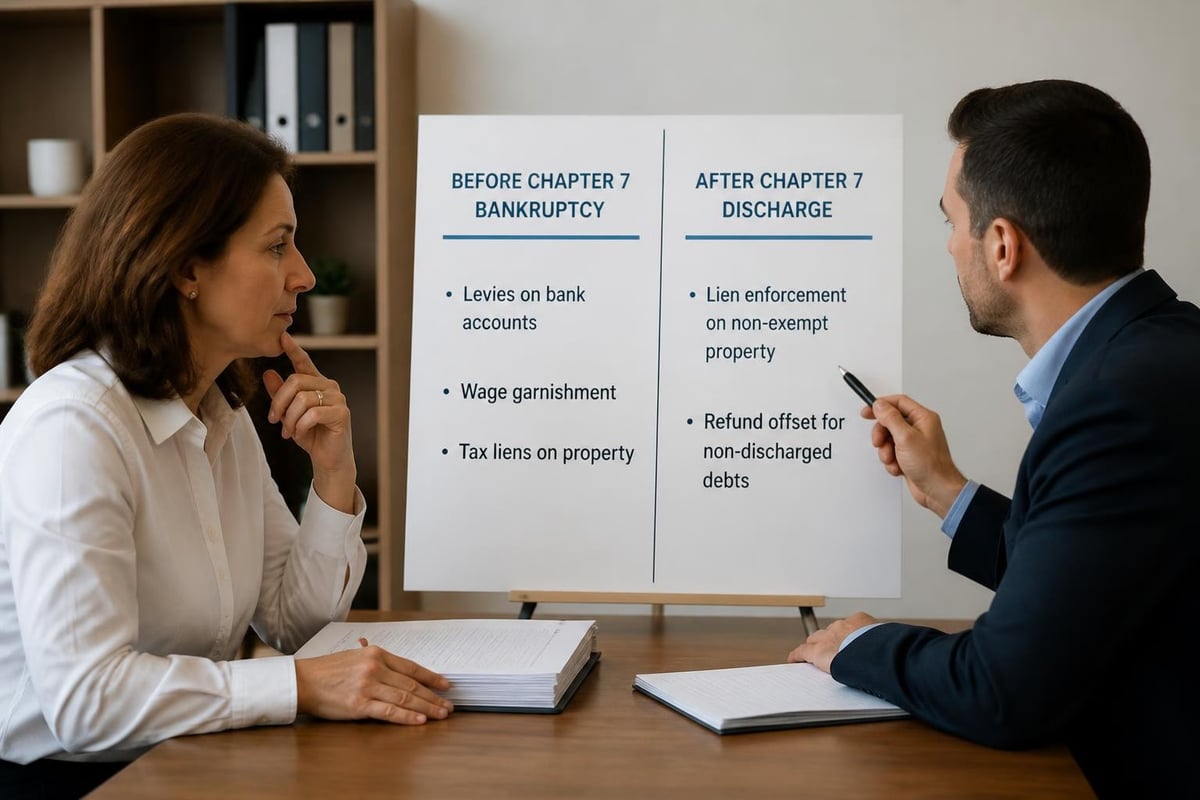
Sometimes waiting isn't an option. Wage garnishment, bank levies, or an imminent foreclosure force your hand. In those cases, Chapter 7 stops collection through the automatic stay even if it doesn't discharge the debt. You buy time. That's worth something, but it's not the same as elimination.
What the IRS Can Still Do After Discharge
Your personal liability is gone, but the IRS retains collection rights against property subject to a lien. They can also collect from future refunds if the lien is still active or if any debt survived discharge. The IRS explains bankruptcy’s effect on tax debt in Publication 908, and it's worth reading before you file.
Post-discharge, the IRS is barred from pursuing you personally. No more levy notices, no wage garnishment aimed at you. But they can levy property encumbered by the lien. They can also offset future refunds against non-discharged debt or against debt secured by a lien. If you owe $15,000 on a lien and you're due a $3,000 refund next year, they'll take it.
If you want the lien removed, you need to satisfy it: pay it in full, wait for the collection statute to expire, or negotiate a withdrawal as part of an installment agreement or Offer. Bankruptcy alone doesn't accomplish this.
Chapter 7 Versus Other Tax Relief Options
Bankruptcy is one tool. It's not always the best. An Offer in Compromise can settle your full debt, including liens, for less than you owe based on your ability to pay. Currently Not Collectible status suspends collection without a bankruptcy filing if you genuinely can't pay. Installment agreements spread the debt over time without the credit hit or asset liquidation.
For small balances under $15,000, the cost and complexity of Chapter 7 often exceeds the benefit. Bankruptcy attorney fees run $1,500 to $3,000 depending on the market. Filing fees add another $338. If your dischargeable debt is only $8,000 and the rest survives, you might end up worse off than if you'd just negotiated a payment plan.
Chapter 7 makes sense when you have multiple years of qualifying income tax debt, limited assets, and no better options. It's also useful when you're drowning in other debt (credit cards, medical bills, personal loans) and the tax debt is a smaller piece. Discharging the other debt frees up cash to deal with the IRS separately.
Recent Case Law and Evolving Interpretations
Courts occasionally split on narrow issues involving tax discharge. Recent Supreme Court filings have addressed circuit disagreements on what constitutes a "return" for discharge purposes and how extensions affect the three-year rule. These cases shape the landscape, but they don't rewrite the core requirements.
The trend is toward stricter interpretation. Courts have repeatedly held that SFRs don't qualify, that late-filed returns must show an honest attempt to comply (not just discharge-motivated filings), and that fraud disqualifies debt even if the IRS never pursued criminal charges. Expecting leniency from the bankruptcy court on tax debt is a mistake.
If your case involves unusual facts, such as a return filed under duress or during an IRS audit with disputed assessments, you need an attorney who knows the case law. General bankruptcy attorneys often miss these nuances. A tax attorney who handles bankruptcy will spot the issues before you file.
Steps to Take Before Filing Chapter 7 for Tax Debt
File every missing return. The IRS won't discharge debt from unfiled years, and the trustee will ask about gaps in your filing history. Getting compliant is the threshold requirement.
Pull your IRS transcripts. You need Account Transcripts for every year you owe. These show the due date, filing date, and assessment date. Without transcripts, you can't calculate the three-year, two-year, and 240-day rules accurately. Request them at IRS.gov or by calling 800-829-1040.
Check for liens. Search the county recorder's office in every county where you own real property. If a lien is on file, it survives discharge. You need to know this going in, not after the bankruptcy closes.
Calculate the dischargeable versus non-dischargeable split. If 80% of your debt survives, Chapter 7 may not be worth it. Run the numbers.
Talk to a tax attorney, not just a bankruptcy attorney. Bankruptcy lawyers know the Bankruptcy Code. Tax attorneys know the IRS rules on discharge and how the IRS behaves post-discharge. You want both skill sets in one conversation, or you want separate counsel working together.
Common Mistakes That Cost Taxpayers the Discharge
Filing before the three-year deadline expires is the most common error. People see their credit collapsing, panic, and file without checking the calendar. That one mistake costs them tens of thousands in non-discharged debt.
Relying on IRS substitute returns is the second mistake. You must file the returns yourself. The IRS will not treat their SFR as your return for discharge purposes. Courts have ruled on this dozens of times. The answer is always the same: no.
Assuming bankruptcy removes the lien is the third. Discharge and lien release are separate. If you're counting on selling your house to fund retirement and you didn't check for a lien, you'll be writing the IRS a check at closing.
When Bankruptcy Isn't the Answer and What to Do Instead
Some clients walk in with $200,000 in payroll tax debt and $12,000 in dischargeable income tax. Chapter 7 doesn't solve that problem. The payroll tax survives, the penalties survive, and they've spent $2,500 on a bankruptcy that accomplished almost nothing.
In those cases, an Offer in Compromise or a structured installment agreement makes more sense. The IRS will settle payroll tax debt if you meet the Offer criteria: your assets and future income can't cover the liability, and paying in full would create hardship. I've settled $400,000 payroll tax cases for under $50,000 when the numbers work.
For taxpayers who simply can't pay anything, Currently Not Collectible status suspends enforcement while you get back on your feet. No trustee, no asset liquidation, no discharged debt showing up on your credit report. It's temporary relief, but it's often smarter than bankruptcy.
How Chapter 13 Compares for Tax Debt
Chapter 13 bankruptcy doesn't discharge tax debt the same way Chapter 7 does. Instead, it forces the IRS into a repayment plan lasting three to five years. Priority tax debt (recent debt that doesn't meet the discharge tests) must be paid in full through the plan. Non-priority tax debt is treated like unsecured debt and might receive only partial payment depending on your disposable income.
Chapter 13 stops collection, including levies and garnishments, through the automatic stay. It also prevents new liens from being filed during the plan. For taxpayers with regular income who need time but can't discharge the debt, Chapter 13 is sometimes the better option.
The downside: you're in bankruptcy for years, not months. You're making trustee payments every month. Your budget is supervised by the court. And if your income drops or you miss payments, the case can be dismissed and the IRS starts collection all over again.
The Automatic Stay and Immediate Relief
The day you file Chapter 7, the automatic stay takes effect. The IRS must stop all collection: no levies, no garnishments, no phone calls. If they violate the stay, the bankruptcy court can sanction them. This is powerful.
For taxpayers facing imminent wage garnishment or a bank levy that would drain their operating account, the automatic stay buys critical breathing room. Even if the tax debt isn't dischargeable, the stay gives you months to negotiate or plan without the IRS hammering you.
The stay lifts when your bankruptcy closes, usually 90 to 120 days after filing in a no-asset Chapter 7 case. Once it lifts, the IRS can resume collection on any debt that survived discharge. But you've had a pause, and you've eliminated your personal liability on the qualifying debt. That changes your negotiating position.
Understanding the Discharge Order and What It Means
When the bankruptcy court issues your discharge order, it lists the types of debts eliminated. Tax debt isn't named individually. The order is general. The IRS determines which specific tax years were discharged based on the statutory tests. They don't always get it right the first time.
After discharge, request a transcript from the IRS showing the account balance for each year. If they're still showing a balance on a year you believe was discharged, you'll need to dispute it. Send a copy of the discharge order, the petition date, and a calculation showing the debt met all five tests. The IRS has a process for post-discharge account adjustments, but you have to push.
Some clients assume discharge means the IRS automatically writes off the debt. They don't. You need to follow up, verify the adjustment, and get written confirmation that the discharged years are closed.
The Credit Impact and Long-Term Consequences
Chapter 7 bankruptcy stays on your credit report for ten years. It's a significant hit. For many clients, their credit is already damaged by tax liens, unpaid debts, or late payments, so the incremental harm is small. For others, especially those with good credit trying to preserve it, bankruptcy is the nuclear option.
Weigh the credit damage against the debt relief. If you're discharging $80,000 in qualifying tax debt plus $60,000 in credit cards and medical bills, the trade might be worth it. If you're discharging $8,000 and tanking your credit for a decade, it probably isn't.
Lenders, landlords, and employers see the bankruptcy. Some won't care. Others will. You'll pay higher interest rates on loans for years. You might struggle to rent an apartment or get approved for a mortgage. These are real costs.
Tax Compliance After Bankruptcy
The bankruptcy court and the IRS expect you to stay current on future tax obligations. If you file Chapter 7, discharge old debt, and then fail to file or pay your 2027 taxes, you're back in the same hole. Worse, the IRS knows you just used bankruptcy, so they'll be less sympathetic to hardship claims.
Set up withholding or estimated payments to avoid a new balance. File every return on time. If you're self-employed or have variable income, work with an accountant to project your liability quarterly and set aside cash. Staying compliant post-bankruptcy is the only way the discharge provides lasting relief.
The trustee may require you to file your current-year return during the bankruptcy and turn over any refund. Plan for that. Don't count on a refund to pay bills if you're in an active Chapter 7 case.
Discharge IRS tax debt bankruptcy Chapter 7 works in narrow circumstances: income tax that's old enough, properly filed, and assessed long enough ago. Most debt doesn't qualify. Liens survive even when the debt is discharged. The process demands precision, and mistakes are expensive. For 32 years, I've walked taxpayers through the calculation and helped them decide whether bankruptcy, an Offer, or another resolution makes sense. If you're weighing Chapter 7 against IRS debt, let's talk: Law Offices of Darrin T. Mish, P.A.