

Knowledge is protection when the IRS is involved. I'm Darrin Mish, a tax attorney in Tampa with 32 years of experience representing taxpayers nationwide. Here's what I want you to understand.
I'm Darrin Mish. Tampa tax attorney, 32 years in, more than $100 million in IRS debt resolved. What follows isn't theory. It's what I've actually watched work.
You filed your return four years ago. You assume the IRS is done looking. Most taxpayers do. But if you left out enough income, you triggered the irs 6 year rule substantial understatement, and the clock hasn't even started winding down yet.
The normal statute of limitations gives the IRS three years from the filing date to audit and assess additional tax. That's 26 U.S.C. §6501(a), the baseline rule. But when you omit more than 25% of your gross income, the assessment period doubles to six years under 26 U.S.C. §6501(e). That's the substantial understatement rule, and it catches people who thought they were safe.
What Counts as a Substantial Understatement Under the 6 Year Rule
The irs 6 year rule substantial understatement kicks in when the amount you omitted exceeds 25% of the gross income stated on your return. Gross income, not net. Not taxable income after deductions. The raw top line.
Say you reported $200,000 in gross receipts on Schedule C. You forgot (or chose to ignore) another $60,000 in deposits. That's 30% of what you reported. The six-year window is now open. The IRS can come back anytime within six years of the filing date to audit that return and assess tax, penalties, and interest.
How the IRS Calculates the 25% Threshold
The math is straightforward, but the application isn't always. The IRS divides the omitted amount by the gross income you actually reported. If that fraction exceeds 0.25, you're in six-year territory.
Key points the IRS follows when applying the test:
- Only income omitted from the return counts, not income you reported incorrectly or undervalued
- Gross income means the figure before any cost of goods sold, deductions, or exemptions
- Partial reporting can still be an omission if the item wasn't adequately disclosed
- Overstatement of basis (claiming you paid more for an asset than you did) counts as omitted income in certain cases
That last point trips up a lot of people. If you sell stock for $100,000 and claim a basis of $80,000 (showing $20,000 gain) but your actual basis was $50,000, you omitted $30,000 in gain. Depending on what else is on your return, that could breach 25%.
The IRS Internal Revenue Manual section on statute-of-limitations rules walks through examples of how examiners apply the six-year period in practice. Revenue agents don't guess. They calculate, document, and justify.
What the IRS Considers "Omitted" vs. "Incorrectly Reported"
Not every understatement of income extends the statute. The irs 6 year rule substantial understatement applies only to income you left off the return entirely, not income you disclosed but computed wrong.
You reported a $50,000 capital gain from selling rental property, but you miscalculated depreciation recapture and the gain should have been $70,000. That's an error, not an omission. The three-year statute still applies. You disclosed the transaction. The IRS had enough information to spot the mistake.
But if you sold that property and never mentioned it anywhere on the return? That's an omission. The six-year clock starts running.
The Adequate Disclosure Exception
Even if you omit an item, you can avoid the six-year rule if you adequately disclosed the transaction in a way that alerts the IRS to the potential issue. Treasury Regulation 26 C.F.R. §301.6501(e)-1 lays out what counts as adequate disclosure.
Filing a Form 8275 (Disclosure Statement) is the safest route. Attach it to your return, describe the item, explain why you're treating it the way you are, and include enough detail that an examiner can evaluate the position without having to dig through your books.
| Disclosure Method | Effect on 6-Year Rule | When to Use |
|---|---|---|
| Form 8275 attachment | Prevents extension if adequately detailed | Uncertain positions, aggressive interpretations |
| Schedule detail (e.g., Schedule D breakdown) | May prevent extension if item and amount clearly stated | Routine transactions with full reporting |
| No disclosure | Six-year rule applies if omission exceeds 25% | Never advisable when in doubt |
Adequate disclosure doesn't mean the IRS agrees with your tax treatment. It just means they had fair notice of what you did, so they can't claim you hid it. The three-year statute applies, even if they later decide you were wrong.
Common Situations That Trigger the IRS 6 Year Rule Substantial Understatement
I've seen the irs 6 year rule substantial understatement come up in patterns. Certain fact patterns show up again and again when the IRS extends the statute.
Scenarios that frequently breach the 25% threshold:
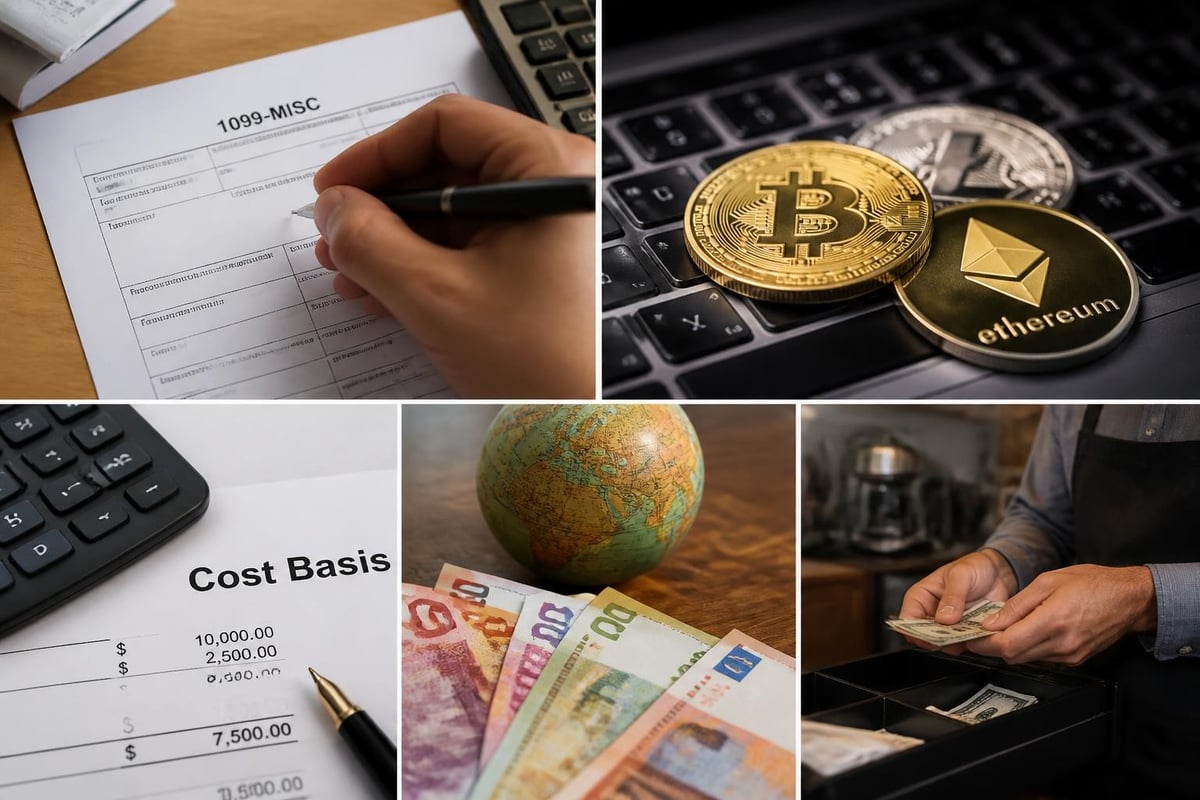
- Unreported 1099 income. Contractor gets paid $80,000 across multiple clients, reports $50,000, "forgets" the rest.
- Cryptocurrency sales. You cashed out $200,000 in Bitcoin gains, reported $40,000 in W-2 wages, didn't mention the crypto anywhere.
- Overstated basis in stock or real estate sales. Reported basis inflated by $150,000 on a $400,000 sale.
- Foreign income or foreign accounts. Omitted $100,000 in offshore income while reporting $300,000 domestically.
- Cash business receipts. Reported $120,000 in gross receipts, bank deposits show $180,000 with no explanation for the gap.
The IRS guidance on examination controls for substantial omissions includes examples that mirror these situations almost exactly. Revenue agents are trained to spot them.
The Foreign Asset Exception and the $5,000 Rule
If the omitted income relates to foreign financial assets and you didn't file the required information returns (like Form 8938 or FinCEN Form 114), the IRS gets an even longer statute. But there's a wrinkle.
For purposes of the 25% test on foreign income, some IRS guidance suggests the threshold is $5,000 in absolute terms, not 25% of gross income. The Congressional Research Service report on statutes of limitations for tax assessment reviews this exception in detail. If you omit any amount of income attributable to foreign financial assets and you failed to properly disclose those assets, the six-year rule applies regardless of the 25% calculation.
That's a separate trap. Foreign income + unreported foreign accounts = extended statute almost automatically.
What Happens When the 6 Year Rule Applies
Once the IRS determines that the irs 6 year rule substantial understatement applies, they have twice the normal time to finish the audit, issue a notice of deficiency, and assess the tax. That's six years from the later of the due date or the actual filing date.
Filed your 2020 return in April 2021? The six-year statute expires in April 2027. Filed it late in October 2021? The clock runs until October 2027. The IRS doesn't rush. They'll use the time if they need it.
What the extended statute means in practice:
- The IRS can audit and assess tax anytime before the six-year deadline
- Penalties and interest continue to accrue during the entire period
- You can't rely on "it's been four years, they're not coming" as a defense
- Audit representation becomes more complicated because records are older and harder to reconstruct
I've represented clients who got audit notices five and a half years after filing. They'd moved twice, changed banks, lost receipts. The IRS doesn't care. If the statute is still open, they're coming.
Can the Statute Be Extended Beyond Six Years?
Yes. If you sign a Form 872 (Consent to Extend the Time to Assess Tax), you give the IRS more time voluntarily. Revenue agents request these extensions when an audit is running long and the statute is about to expire.
You're not required to sign. But if you refuse and the agent isn't finished, they'll likely issue a notice of deficiency based on whatever information they have, which is usually worse for you than cooperating. It's a leverage game.
The six-year rule also doesn't apply if the IRS can prove fraud. Fraud opens the statute indefinitely under 26 U.S.C. §6501(c)(1). No time limit at all. But fraud requires intent to evade tax, not just negligence or mistakes. The IRS has to prove you knew what you were doing and did it anyway.
How Courts Have Interpreted the Substantial Omission Rule
The irs 6 year rule substantial understatement isn't just an IRS preference. It's statutory law, and courts enforce it. But they also interpret what "omission" means, and those interpretations matter.
In *Acqis Technology v. Commissioner* (T.C. Memo. 2024-21), the Tax Court analyzed whether an overstatement of basis constituted an omission of gross income for purposes of the six-year rule. The court sided with the IRS, holding that inflating basis to reduce gain effectively omits income, even though the transaction itself was disclosed.
That case reinforced what many practitioners already understood: the IRS doesn't just count what you left blank. They count what you should have reported but didn't, including income buried in a misstated basis figure.
Recent Regulatory and Statutory Changes
The six-year rule has been around for decades, but the IRS and Treasury keep refining how it applies. The AICPA’s analysis of recent amendments to §6501 discusses changes that affect when the statute opens and closes, particularly for partnership and S corporation items.
Some of those changes aren't retroactive. If your return was filed before a regulatory amendment took effect, the old rules might still apply. That's both good and bad. Good if the new rule is harsher. Bad if the old rule gave the IRS more leeway.
The Treasury Department’s General Explanations for Fiscal Year 2025 describes the policy goals behind the six-year rule: giving the IRS enough time to detect underreporting while balancing the taxpayer's need for finality. The rule isn't punitive on its face. It's designed to account for the fact that large omissions are harder to detect quickly.
What You Should Do If You Omitted Income on a Past Return
If you're reading this and realizing you left income off a return filed within the last six years, you have options. None of them involve pretending it didn't happen.
The safest move is filing an amended return (Form 1040-X) before the IRS finds the omission. Voluntary disclosure doesn't erase the tax or interest, but it usually reduces penalties and keeps you out of criminal territory. The IRS treats self-correction far more favorably than discovered underreporting.
Steps to take when you discover an omission:
- Calculate the actual omission. Figure out exactly how much income you left off and whether it crosses the 25% threshold.
- Determine if the six-year statute is still open. Count six years from the filing date (or due date if you filed early).
- Gather supporting records. Bank statements, 1099s, transaction records, anything that documents the omitted income.
- File an amended return if the statute is still open. Use Form 1040-X and include a detailed explanation of the correction.
- Pay the tax and interest when you file the amendment. Paying upfront reduces penalties and shows good faith.
If you're already under audit and the agent is raising the six-year rule, you're in a tougher spot. At that point, the question isn't whether to fix it. It's whether the IRS calculated the omission correctly and whether adequate disclosure (or another exception) keeps you in the three-year window.
When the Statute Has Already Closed
If the six-year statute expired and the IRS never assessed the tax, you're generally safe. The IRS can't assess tax after the statute closes unless they can prove fraud or you signed an extension.
But "closed statute" doesn't mean "no consequences." If the omitted income shows up in a later year's audit, the IRS might use it as evidence of a pattern or to argue fraud in a year where the statute is still open. They can't assess the old year, but they can use it against you.
And if you're applying for an Offer in Compromise or other relief, undisclosed omissions from closed years can torpedo your credibility. The IRS expects full honesty, even about years they can't touch anymore.
How the 6 Year Rule Affects Liens, Levies, and Collection
The irs 6 year rule substantial understatement extends the IRS's time to assess tax. It doesn't directly extend the time to collect tax once it's assessed. Those are two different statutes.
Assessment has to happen within the statute (three or six years, depending on the facts). Once the IRS assesses, they have ten years to collect under 26 U.S.C. §6502. The collection statute starts running from the assessment date, not the filing date.
So if the IRS waits five and a half years to assess under the six-year rule, you're looking at fifteen and a half years total from the filing date before the debt expires (five and a half to assess, ten to collect). That's a long time to live with IRS liens and wage garnishment risk.
| Statute Type | Time Limit | Starts Running From | What It Covers |
|---|---|---|---|
| Assessment (normal) | 3 years | Filing or due date | IRS must assess tax by this deadline |
| Assessment (substantial omission) | 6 years | Filing or due date | IRS must assess if 25%+ income omitted |
| Collection | 10 years | Assessment date | IRS must collect assessed tax by this deadline |
Understanding these timelines matters if you're negotiating with the IRS or considering whether to wait out the statute. Waiting only works if the assessment statute expires before they find the problem. If they assess within the six-year window, you've got another decade of collection exposure.
Statute of Limitations vs. Statute of Frauds
One last trap: confusing the statute of limitations with the statute of frauds. They're not related.
The statute of limitations (what we've been discussing) is the IRS's deadline to assess tax. The statute of frauds is a contract law principle about enforcing agreements. It has nothing to do with tax collection or the irs 6 year rule substantial understatement.
People mix them up because "fraud" appears in both contexts. If the IRS alleges civil fraud, the statute of limitations disappears entirely under 26 U.S.C. §6501(c). That's not a statute of frauds issue. That's an exception to the normal assessment deadline.
Fraud, for IRS purposes, means you intentionally tried to evade tax. Omitting income might be fraud, or it might be negligence, or it might be an honest mistake. The IRS has to prove intent. Negligence and mistakes still trigger the six-year rule if the 25% threshold is breached, but they don't open the statute indefinitely.
The irs 6 year rule substantial understatement doubles the IRS's audit window when you omit more than 25% of gross income, and it applies more often than most taxpayers expect. The calculation is mechanical, the consequences are real, and waiting doesn't make the problem disappear. For 32 years I've helped clients navigate these rules, fix past mistakes, and defend against IRS overreach when the facts support it. If you've omitted income or received an audit notice raising the six-year rule, let's talk. Law Offices of Darrin T. Mish, P.A. offers free initial consultations, and we represent taxpayers nationwide.