

I'm Darrin Mish. For 32 years I've practiced federal tax litigation — routine audits, Tax Court cases, and everything in between. If you're facing an IRS issue, here's what you need to know first.
I'm Darrin Mish. Tampa tax attorney, 32 years in, more than $100 million in IRS debt resolved. What follows isn't theory. It's what I've actually watched work.
The IRS doesn't have forever to come after you for unpaid taxes. They have a deadline. That deadline is controlled by the irs 3 year assessment statute of limitations ased, and understanding this clock is critical if you're facing an audit, unfiled returns, or just trying to figure out when the IRS can no longer assess additional tax. The Assessment Statute Expiration Date (ASED) is the hard stop on when the IRS can legally assess tax. After it expires, they're done. You walk.
What the IRS 3 Year Assessment Statute of Limitations ASED Actually Means
The irs 3 year assessment statute of limitations ased refers to the general rule that the IRS has three years from the date you file your return to assess additional tax. Assessment means the IRS formally records the tax liability on their books. It's the official step that starts the collection machinery. Without an assessment, the IRS can't issue a notice of federal tax lien or a levy.
The three-year window starts ticking the moment your return is filed. If you file early, the clock starts on April 15 (or the actual filing deadline for that year). If you file late, it starts when the IRS receives your return. The statute is codified in 26 U.S.C. § 6501, which lays out the basic rule and the exceptions that can extend it or wipe it out entirely.
The IRS explains the assessment statute in simpler terms on their consumer guidance page, but the core concept is straightforward: file your return, and the IRS has three years to challenge it. Miss that window, and the tax year is closed.
When the Clock Starts Running
Your ASED begins on the later of two dates: the date you actually filed the return, or the due date of that return (ignoring extensions). This matters if you file early. Say you file your 2025 return on February 1, 2026. The three-year clock doesn't start until April 15, 2026. The IRS gets the full three years from the due date, not the filing date.
If you file late, the clock starts when the return hits the IRS. File your 2025 return on October 1, 2027, and the ASED runs from October 1, 2027, expiring October 1, 2030. You don't get credit for the gap.
Returns filed before the due date are treated as filed on the due date for statute purposes. The IRS clarifies this in guidance on assessment timelines, and it's a trap for people who think filing early buys them extra time. It doesn't.
Common Exceptions That Extend the IRS 3 Year Assessment Statute of Limitations ASED
The three-year rule is just the baseline. The statutory text of 26 U.S.C. § 6501 includes multiple exceptions that stretch the ASED or eliminate it entirely. These exceptions are where the IRS does most of its damage.
The Six-Year Rule for Substantial Omissions
If you omit more than 25% of your gross income on a return, the IRS gets six years to assess tax. Not three. Six. This is the substantial omission rule, and it applies to both individuals and businesses. Gross income is the figure before deductions, so the 25% threshold can be easier to hit than you think.
Example: you report $100,000 in gross income on your 2025 return but actually earned $140,000. You omitted $40,000, which is 40% of what you reported. The IRS now has until April 15, 2032, to assess tax on that return. Not 2029. The clock just doubled.
The six-year rule applies to both underreported income and overreported basis in securities transactions. If you sell stock and inflate your basis to reduce the gain, and that error exceeds 25% of gross income, you're in six-year territory.
| Scenario | Omission Amount | Gross Income Reported | Percentage | Statute Period |
|---|---|---|---|---|
| Normal filing | $0 | $100,000 | 0% | 3 years |
| Minor error | $20,000 | $100,000 | 20% | 3 years |
| Substantial omission | $30,000 | $100,000 | 30% | 6 years |
| Fraud | Any amount | Any amount | N/A | No limit |
No Return, No Statute
If you never file a return, the irs 3 year assessment statute of limitations ased never starts. The IRS can assess tax 10 years from now, 20 years from now, whenever they get around to it. The clock only begins when you file. This is why filing unfiled returns is always the first step in resolving old tax debt, even if you can't pay.
Some taxpayers think they can wait out the IRS. They can't. The statute doesn't run on an unfiled return, and the IRS will eventually file a substitute return (SFR) on your behalf. That SFR starts a statute, but it's not your return, and it won't include deductions or credits you're entitled to. You're assessed based on the IRS's worst-case reconstruction of your income.
Fraud and Willful Tax Evasion
If the IRS proves fraud or a willful attempt to evade tax, the statute disappears entirely. The government can assess tax at any time. Fraud is a high bar, it requires intent and affirmative acts to deceive, but once proven, the three-year and six-year rules are irrelevant.
The IRS rarely pursues fraud for civil assessment purposes. Criminal prosecution is another story. But in civil cases, if they can prove fraud, they will. I've seen it used to reach back a decade or more on taxpayers who thought they were safe.
What Stops or Suspends the ASED
Certain taxpayer actions or IRS proceedings can pause or extend the irs 3 year assessment statute of limitations ased. These aren't exceptions in the sense of replacing the three-year rule. They're events that freeze the clock or push the expiration date forward.
Statute Extensions You Sign (Form 872)
The IRS can ask you to extend the statute voluntarily. They'll present Form 872, Consent to Extend the Time to Assess Tax. Sign it, and the ASED moves to whatever date the form specifies. This is common in audits when the IRS needs more time to finish its examination before the statute runs.
You're not required to sign an extension. But if you refuse, the IRS will assess tax based on whatever information they have, even if incomplete. That assessment might be inflated, and you'll spend years fighting it in Tax Court or appeals. Sometimes it's smarter to extend and finish the audit properly.
Extensions are also common when you're negotiating an Offer in Compromise or installment agreement. The IRS wants to keep the statute open while they review your financials. If the statute expires during the negotiation, they lose leverage.
Bankruptcy and Collection Due Process
Filing bankruptcy suspends the irs 3 year assessment statute of limitations ased for the period of the bankruptcy plus six months. The IRS can't assess tax while you're in bankruptcy, so the clock stops. Same rule applies if you request a Collection Due Process (CDP) hearing after the IRS issues a levy or lien notice.
The suspension is automatic. You don't need to do anything to trigger it. But you do need to account for it when calculating your ASED. If your statute was set to expire on April 15, 2029, and you file bankruptcy in January 2029, that expiration date gets pushed out by the length of the bankruptcy case plus 180 days.
Amended Returns and Claims
Filing an amended return doesn't restart the irs 3 year assessment statute of limitations ased. The original ASED still controls. But it does open a narrow window for the IRS to assess additional tax related to the items you amended. That window is 60 days from the date the IRS receives the amended return, or the original ASED, whichever is later.
So if your ASED is April 15, 2029, and you file an amended return on March 1, 2029, the IRS has until at least May 30, 2029, to assess tax on the amended items. The 60-day rule extends the statute just enough to let the IRS respond to your amendment.
How the IRS Tracks and Enforces the Assessment Statute
The IRS maintains an internal database that tracks every taxpayer's ASED by year. Revenue agents and officers see the ASED date on their case management screens. It's a hard deadline. Miss it, and the assessment is barred. The IRS takes it seriously because failing to assess before the statute expires means the tax is uncollectible forever.
According to a Treasury Inspector General report on statute controls, the IRS has automated alerts that flag cases approaching their ASED. Managers review these cases monthly to decide whether to assess, request an extension, or close the case. The controls have improved over the last decade, but mistakes still happen.
If the IRS assesses tax after the statute expires, you can challenge the assessment in Tax Court or file a claim for refund. The government will concede. An untimely assessment is void. I've won cases on statute defenses alone, no need to fight the underlying tax liability.
What Happens When the ASED Expires
When the irs 3 year assessment statute of limitations ased expires, the IRS loses the legal authority to assess additional tax for that year. They can't issue a notice of deficiency. They can't adjust your return. They can't assess penalties or interest. The year is closed.
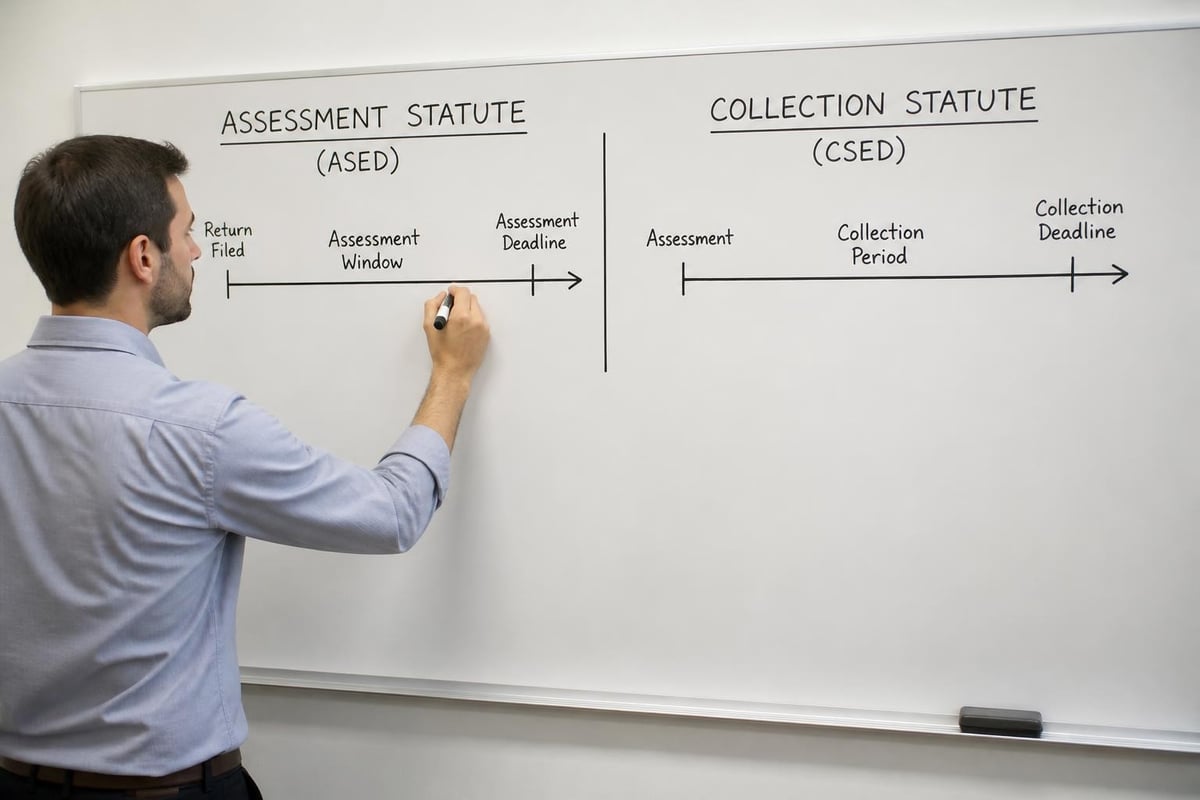
But the statute expiring doesn't erase tax you already owe. If the IRS assessed tax before the statute ran, they have 10 years to collect it (that's a different statute, the Collection Statute Expiration Date or CSED). The ASED only limits assessment, not collection.
Taxpayers sometimes confuse these two deadlines. The ASED controls when the IRS can create a new tax liability. The CSED controls how long they can pursue a liability that already exists. They're separate clocks, and they often run simultaneously.
Why Practitioners and Taxpayers Need to Monitor the ASED
You can't assume the IRS is tracking your statute correctly. Errors happen. The IRS miscalculates the start date, overlooks an extension, or fails to credit a suspension period. If you're in an audit or facing wage garnishment or a levy, knowing your ASED gives you leverage.
A KPMG refresher article on tax statutes emphasizes that practitioners should calculate the ASED independently, not rely on IRS transcripts. Transcripts often show the wrong date because the IRS hasn't updated its records to reflect extensions or suspensions.
I pull transcripts on every new client and calculate the ASED myself. It's basic due diligence. If the IRS is about to run out of time, that changes the entire strategy. You can wait them out. If the statute has years to run, you negotiate.
How to Verify Your ASED
Order your tax account transcript from the IRS. It will show your return filing date and the current ASED the IRS has on file. Cross-check that date against the three-year rule (or six-year, if applicable). Add any extensions or suspension periods you know about.
If the IRS date doesn't match your calculation, request a correction. The IRS won't volunteer to shorten the statute, but if you can prove they're wrong, they'll adjust it. I've had cases where the IRS claimed an ASED years beyond what the statute allowed. A single letter with the correct calculation fixed it.
| Document Needed | Why You Need It | Where to Get It |
|---|---|---|
| Tax account transcript | Shows IRS's recorded ASED and filing date | IRS.gov or Form 4506-T |
| Return filing proof | Confirms actual filing date if disputed | Certified mail receipt or e-file confirmation |
| Form 872 copies | Documents any statute extensions you signed | Your records or IRS case file |
| Bankruptcy discharge | Proves suspension period for ASED calculation | Bankruptcy court records |
Policy Debates and Proposed Changes to the Assessment Statute
The irs 3 year assessment statute of limitations ased has been stable for decades, but recent policy discussions have floated the idea of extending it. The Treasury Department’s General Explanations for FY2025 included a proposal to extend the statute in certain international tax cases and for digital asset transactions, arguing that modern tax schemes are more complex and harder to detect within three years.
A law review article on statute reform argues the opposite: technology has made audits faster, and the IRS should shorten the statute to reduce taxpayer uncertainty. The article points out that the IRS already has tools to catch underreporting quickly (automated matching, third-party reporting), and a shorter statute would force the agency to act faster.
Congress hasn't passed any changes yet. The three-year rule remains the baseline, and it's unlikely to change in the near term. But practitioners should watch for legislative proposals, especially around cryptocurrency taxes and offshore accounts, where the IRS is lobbying for more time.
Practical Implications for Taxpayers Facing Audits or Assessments
If you're in an audit and the ASED is approaching, the IRS will rush. They'll push for quick agreements, threaten immediate assessment, and pressure you to extend. That pressure is a sign you have leverage. The closer the statute, the weaker their position.
Don't extend the statute unless you're getting something in return. If the IRS needs more time, ask for concessions: drop certain penalties, agree to a lower adjustment, or commit to a faster resolution. An extension buys them time. Make them pay for it.
If the statute expires during an audit, the IRS will assess whatever they've proposed so far, even if they haven't finished the examination. That's called a "protective assessment," and it preserves their right to collect on the proposed adjustments while they finish the audit. You can challenge the assessment later, but they've locked in the tax.
What to Do If the IRS Misses the Statute
If the IRS assesses tax after your ASED expires, challenge it immediately. File a claim for refund or petition Tax Court (depending on the stage of collection). Raise the statute as an affirmative defense. The IRS will concede or the court will rule in your favor. An untimely assessment is legally void.
I've defended cases where the IRS assessed tax five years after the statute expired. They didn't catch the error until we pointed it out. The assessment was reversed, the liability disappeared, and the client owed nothing. That's the power of the statute.
How the IRS 3 Year Assessment Statute of Limitations ASED Affects Collection and Settlement
Even if the IRS assesses tax before the ASED expires, the expiration of the assessment statute affects settlement negotiations. The IRS is more willing to compromise on older liabilities because they have limited time to collect (under the CSED). If a tax year is about to fall off the assessment statute, the IRS will either assess immediately or let it go.
When evaluating Offers in Compromise or penalty abatement requests, the IRS considers how much time is left on both the ASED and the CSED. If the statute is short, they'll accept less. If they have years to collect, they'll demand full payment or a high monthly installment.
Knowing your ASED also helps you decide whether to fight or settle. If the statute is about to expire and the IRS hasn't assessed, waiting might be the smartest move. If they've already assessed and the collection statute is long, settling is usually better than dragging it out.
The irs 3 year assessment statute of limitations ased is your shield against endless IRS examinations, but only if you know when it starts, when it ends, and what can extend it. For 32 years, I've used statute defenses to close cases the IRS thought were still open. If you're facing an audit, unfiled returns, or a surprise assessment, and you're not sure where you stand on the clock, let's talk. Law Offices of Darrin T. Mish, P.A. offers free initial consultations, and we work with clients nationwide to resolve IRS debt and shut down improper assessments.